Insight

Uninsured Motorist Coverage: Making Smart People Feel Dumb

Published on: July 28, 2017
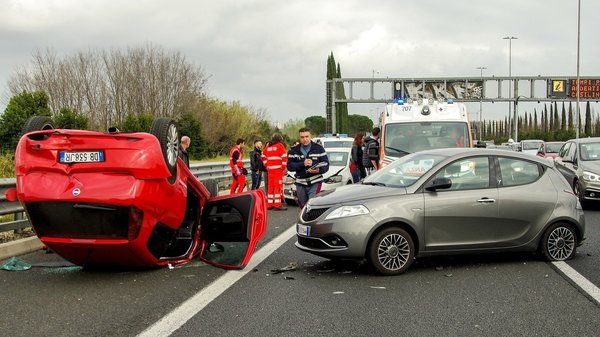
I have met smart, sophisticated “business” people whose eyes glass over when they try to explain their understanding of “UM” coverage. The picture becomes murkier when discussing “economic-only UM,” a form of UM coverage many people purchase without even knowing it. Through many years and conversations, I have come to conclude that there is a general fogginess that obscures this entire subject with many, if not most, people. This blog is an effort to improve understanding on the subject.What is “UM” Coverage?“UM” signifies “uninsured motorist” insurance coverage, but is more properly described as “uninsured/underinsured” motorist coverage. A person, family, business, or group purchases UM coverage to respond to damages caused in an accident by someone who has either no insurance or not enough to cover the loss. You purchase UM insurance to protect yourself or those connected to you. Without UM, you are gambling that the person who caused the accident (the “tortfeasor”) will have insurance coverage, and enough coverage, to respond to the injuries and damages they have caused.Why UM?This question is simply answered in a two-part response:#1- The roads are dangerous-Unless you are a crop duster or an undercover agent, the most dangerous thing you will likely do on any given day is to drive on a public road, even more so in the age of “smartphones” and distracted-driving.#2- Many drivers lack sufficient liability coverage- An unhealthy portion of drivers have either no insurance on insufficient insurance coverage to address an accident involving severe injuries or damages. The State of Louisiana requires motorists to obtain at least the minimum insurance of $15,000 “per person,” $30,000 “per accident,” and $25,000 to address property damage. If you do not purchase UM, you are trusting that these limits will be enough, as they might be in a minor accident. But what if the injuries are severe or you have multiple passengers in your car, van, or suburban?Often, the same people who reject UM, will buy “collision” coverage on their car to make sure they are not left paying for a car note after the car is destroyed in an accident. In this limited way, you can think of UM insurance as collision coverage on you, your family, passengers, or employees.While perfect statistics are not available, many drivers on the road have no insurance. Frequently, drivers will obtain minimum limits insurance through a “premium finance” arrangement, but will have stopped paying the premiums (thereby losing coverage) by the time of an accident.What is “Economic-Only” UM?In Louisiana, UM coverage will be afforded to you unless you “waive” the coverage under La. R.S. 22:1295. Louisiana residents are presented with a form that allows them to waive or select UM coverage. They are also allowed to select “economic-only” UM. People often choose this option because it is cheaper, but economic-only UM coverage will only pay for economic damages such as lost wages, medical bills, funeral costs, and other monetary damages. Economic-only UM will not pay money to compensate for pain and suffering/mental anguish, scarring and disfigurement, or other non-economic damages.FAQS

  • Can UM protect me from a hit-and-run driver? Yes.
  • What if another driver’s negligence caused the accident, but there was no physical contact with that driver’s vehicle and they fled? In this scenario, UM may be available under La. R.S. 22:1295(1)(f); however, you will need to identify an “independent and disinterested witness” to establish the actions of the unidentified driver.
  • Will UM protect me if I am at fault in an accident? No. The law would consider that a “moral hazard” and invite unscrupulous individuals to cause an accident in hopes of recovering under the policy they purchased.
  • Will UM protect me if I am a pedestrian? It may, depending upon the terms of your insurance policy.
  • What if an object falls from a vehicle and causes an accident? UM may be available in this circumstance. The ultimate answer may depend upon whether the “falling object” had come to rest before the accident. Rener v. State Farm Mut. Auto. Ins. Co., 99-1703 (La.App. 3 Cir. 4/05/2000), 759 So.2d 214, 215.

CONCLUSIONRational people may decide to reject UM to save money; and this decision may be the right one if they have health insurance, short-term disability, long-term disability, or others such protections. However, people often make such decisions with less than full information. Hopefully, you will make the smart choice.

Posted by:

Disclaimer

Keogh Cox & Wilson, Ltd. provides this blog as a public service for general information only. The materials contained herein may not reflect the most current legal developments or even express the opinion of all or even most of Keogh Cox attorneys. Such material does not constitute legal advice or form any attorney-client relationship. Keogh Cox and all contributing author(s) expressly disclaim all liability to any person with respect to the contents of this Web site and Blog and expect that no reliance will be made upon the information provided.
Continue Reading

Explore legal perspectives on the issues shaping Louisiana's key industries and courtrooms.

Insight

What ifs….. Indemnifying Premises Liability Exposure

If you are a property owner, stop and think about the “what ifs” before you enter into a lease with a property manager or lessee. For example, what if an invitee of the property that you own is hurt while on and/or because of a condition on the property? Who is responsible?

A property owner may be able to transfer its potential liability to a property manager or lessee of the property if the lease contains an indemnification provision. However, not all indemnification provisions are enforceable, and these critical provisions are often litigated.

The Eastern District Court of Louisiana recently enforced an indemnification provision, granting summary judgment to a landowner who sought indemnification from its property lessee in Avila v. Village Mart, LLC, Civ. A. No. 20-1850, 2021 WL 4439579 (E.D. La. 9/28/21). In the case, a shopping center leased retail space to a men’s store. Before the store opened, a painter was injured when he fell from a ladder. The owner of the shopping center argued that the lessee owed a defense. It argued indemnity applied because the plaintiffs’ claims arose out of the lessee’s buildout construction, over which the owner did not have any care, custody, or control.

In response, the lessee argued that the owner was not entitled to indemnification because the plaintiffs’ claims did not “arise out of or were connected with Tenant’s use, occupancy, management or control of the Leased Premises.” The lessee claimed that it was not using, occupying, managing, or controlling the leased space because the only permitted use of the space was to sell menswear, and the space was not being used for this purpose at the time of the accident.

Louisiana courts often apply a “but for” causation test to such “arising out of” language in indemnity provisions. Avila, 2021 WL 4439579, at *5, citing Kan. City S. Ry. Co. v. Pilgrim’s Pride Corp., No. 06-03, 2010 WL 1293340, at *6 (W.D. La. Mar. 29, 2010), and Perkins v. Rubicon, Inc., 563 So.2d 258, 259-60 (La. 1990). The court observed the lessee’s arguments contradicted language in the lease that allowed the lessee to use and occupy the store before it opened to the public. The lease also explained that the lessee was responsible for certain construction work and identified specific dates to begin work and to open the store. Thus, the lease contemplated use and occupancy before the store was open to the public. The court found that the lessee’s possession of the space and its construction obligations under the lease established its use and occupancy of the space. The court stated:

Given the broad language in the indemnity agreement – ‘arising out of or connected with’ – [the plaintiffs’] injuries, resulting from his work as a subcontractor painting the premises leased by [the retail space lessee,] are connected to [its] use and occupancy of the premises. … Because [the retail space lessee] was in possession of the space, and had assumed responsibility for the buildout and for contractors and subcontractors working on the buildout, the Court finds that the plaintiffs’ liability theories fall within the scope of the indemnity provision in the lease. Avila, 2021 WL 4439579, at *6.

The enforceability of indemnity provisions such as the one examined in Avila will continue to be litigated. In the meantime, Avila reminds us of the importance of sound indemnity language to anticipate the “what ifs.”

Insight

Louisiana Legislature Enacts Changes to Bad Faith Statutes

The Louisiana Legislature recently enacted Act 3, which reflects an effort to address the handling of insurance claims in Louisiana – particularly for catastrophic losses – and define ambiguities in the law. This blog addresses changes to Louisiana’s “bad faith” statutes. Broadly, Act 3 amends and enacts new sections of La. R.S. 22:1892, repeals La. R.S. 22:1973, and enacts La. R.S. 1892.2 to address situations involving catastrophic losses.

Prior Louisiana Bad Faith Statutes – La. R.S. 22:1892 and La. R.S. 22:1973

Previously, La. R.S. 22:1892(A) stated an insurer must:

  • Issue payment to an insured within 30 days of receipt of satisfactory proof of loss;
  • Pay the amount of a bona fide third-party’s property damage or reasonable medical expenses within 30 days of a written settlement agreement;
  • Initiate loss adjustment within 14 days of notice of a non-catastrophic loss or within 30 days of receipt of notice of a catastrophic loss;
  • Make a written offer to settle property damage within 30 days of receipt of satisfactory proof of loss.

If an insurer did not follow the requirements of La. R.S. 22:1892(A), the insurer could be required to pay the insured the amount owed under the policy plus a penalty if the insured established that the insurer’s conduct was “arbitrary, capricious and without probable cause.” Courts defined this standard as “vexatious” and without justification. The penalty is calculated as either 50% of the amount owed under the policy or 50% of the difference between the amount owed and a partial tender made by the insurer, if any. Additionally, if the insured established entitlement to the penalty, the insured could also recover attorneys’ fees and costs from the insurer.

Former La. R.S. 22:1973 codified an insurer’s duty of good faith and fair dealing. It set an affirmative duty to adjust claims fairly and promptly and make reasonable efforts to settle claims with the insured, a claimant or both. This general duty of good faith and fair dealing applies only to insureds.^ The statute also outlined six prohibits acts that, if knowingly performed, constituted a violation of the statute. Five of these six prohibited acts applied to both insureds and third-party claimants.^*

If an insured proved a knowing violation of La. R.S. 22:1973, the insurer could be required to pay the amount owed under the policy, damages caused by the insurer’s violation of the statute and a penalty of up to 200% of the damages that the insured or claimant incurred as a result of the breach. Such damages were separate and distinct from the amounts owed under the policy but could extend to anything for which the insured could establish a causal link.˚̃

Revisions to La. R.S. 22:1892

The new revisions enact several important changes. While the text of the new statute should be considered when evaluating any pending or potential claims, a summary is provided here.

  1. Time Delays

Under amended and re-enacted La. R.S. 22:1892(A), insurers must generally adhere to the time delays and conduct outlined under the previous law. Under La. R.S. 22:1892.2, for catastrophic events at residential properties, an insurer’s payment is owed within 60 days of receipt of satisfactory proof of loss. For catastrophic losses at non-residential properties, the statute provides an insurer’s payment is owed within 90 days of receipt of satisfactory proof of loss.

Another exception exists when an insurer initiates loss adjustment before the 14-day or 30-day deadline. If this occurs, the insurer’s obligation to issue a written offer to settle is extended by the number of days the insurer initiates loss adjustment before the deadline.

  1. Reciprocal Duty of Good Faith

Under the new law, La. R.S. 22:1973 is repealed and the general duty of “good faith and fair dealing” owed by an insurer to its insured and the prohibited insurer conduct previously outlined in La. R.S. 22:1973 is now encompassed within §1892.

The new statute also provides that the insured, the claimant or the representative of the insured/claimant owes the duty of good faith and fair dealing. If an insured fails to comply with affirmative duties under the policy, misrepresents pertinent facts and coverages, submits an estimate that lacks a basis in the evidence or the policy, then the insured’s conduct may be considered in determining whether the insurer’s conduct warrants an award of penalties.

  1. Cure Period

For catastrophic losses, the new law states suits may only be brought if the insured first provides the insurer with “cure period notice.” This notice requires that the insured provide the insurer with written notice of the violation, a written formal demand and notice of the facts and circumstances of the dispute. After this notice, several options exist:

  1. The insurer can pay the demand in full (along with the insured’s actual expenses and attorney fees no greater than 20%) within 60 days of the notice and extinguish any further cause of action.
  • The insurer can issue partial payment on the claim within 60 days of the notice and reduce the penalty owed, if any, by half.
  • The insurer can request additional information, but this does not extend the insurer’s other deadlines.
  1. Revised Penalty Provisions

The amendments also modify the recoverable penalty. The statute specifies the calculation of the penalty based on the type of violation, the type of property and the type of loss event. Generally, the insured is no longer entitled to recover all damages sustained by a breach of the statute: now the claimant may only recover “proven economic damages.” Notably, the potential for a penalty of up to 200% of the damages sustained as a result of the breach no longer exists.

  1. Timing

The law also formalizes and codifies the prescriptive period for claims brought under La. R.S. 22:1892 or La. R.S. 22:1892.2 to two years.

References:

^Theriot v. Midland Risk Ins. Co., 1995-2895 (La. 5/20/97) 694 So.2d 184.

* Team Contractors, L.L.C. v. Waypoint NOLA, L.L.C., 780 Fed.Appx. 132 (5th Cir. 2019).

˚Durio v. Horace Mann Ins. Co., 2011-0084 (La. 10/24/11) 74 So.3d 1159.

̃ Audubon Orthopedic and Sports Medicine, APMC v. Lafayette Ins. Co., 2009-0007 (La.App. 4 Cir. 4/21/10) 38 So.3d 963.

Insight

Louisiana Legislature Sets New Prescription Period for Tort Claims

The Louisiana legislature recently enacted laws that set new prescription periods for most delictual/tort actions and claims for damage caused to immovable property. Civil Code articles 3492 and 3493 previously established a prescription period of one year for these types of claims. The legislature repealed these articles and enacted Louisiana Code Articles 3493.1 and 3493.2 in their place.

Louisiana Code Article 3493.1 now establishes a prescriptive period of two (2) years for delictual actions/tort claims that runs from the day injury occurred or damage is sustained. It contains language previously included in Louisiana Civil Code Article 3492, which states that prescriptive period does not run against minors or interdicts in actions involving permanent disability and brought pursuant to the Louisiana Products Liability Act or state law governing product liability actions in effect at the time of the injury or damage.

Louisiana Civil Code Article 3493.2 also establishes a prescriptive period of two (2) years when damage is caused to immovable property. This prescriptive period runs from the day the owner of the immovable acquired, or should have acquired, knowledge of the damage.

These changes went into effect of July 1, 2024. Louisiana Civil Code Articles 3493.1 and 3493.2 apply prospectively only and apply to delictual actions arising after July 1, 2024.

Collin J. LeBlanc

Partner
Insurance
Louisiana
UM Coverage