Insight

Court Finds Real Estate Agents Are Not Required to Research the Truthfulness of Their Client’s Representations

Published on: February 5, 2026

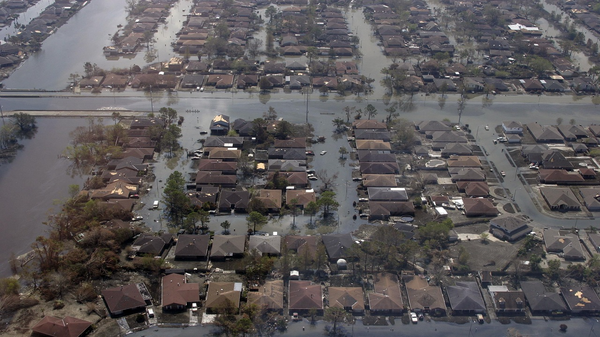
In Smith v. Grantham, homebuyers sued the sellers for alleged failure to disclose prior flooding of the home. The buyers also sued the sellers’ real estate agent for negligent misrepresentation, arguing the realtor knew or should have known of a prior history of flooding. The plaintiff referenced the previous sellers’ property disclosure documents located in the MLS listing database, which disclosed a prior flooding incident. However, the property disclosure document that the realtor received from her clients denied any prior flooding of the property or structure.

The Court of Appeal affirmed summary judgment in favor of the sellers’ agent, noting that her clients represented in their property disclosure document that the property had never flooded, and she had no actual knowledge contradicting their representation. The Court stated that under La. R.S. 9:3894(B), a real estate agent is relieved of liability for providing false information furnished by her client if she did not have actual knowledge that the information was incorrect. The court held that imposing a higher duty on a real estate agent would improperly “create a situation in which the agent had to independently verify information before conveying it to the buyer.”

Reference:

Smith v. Grantham, 93-0881 (La. App. 1 Cir. 9/4/24), 394 So.3d 316.

Posted by:

Disclaimer

Keogh Cox & Wilson, Ltd. provides this blog as a public service for general information only. The materials contained herein may not reflect the most current legal developments or even express the opinion of all or even most of Keogh Cox attorneys. Such material does not constitute legal advice or form any attorney-client relationship. Keogh Cox and all contributing author(s) expressly disclaim all liability to any person with respect to the contents of this Web site and Blog and expect that no reliance will be made upon the information provided.

Continue Reading

Explore legal perspectives on the issues shaping Louisiana's key industries and courtrooms.

Insight

The New Home Warranty Act: Protections and Pitfalls

Louisiana’s New Home Warranty Act (“NHWA”) provides remedies to homeowners forcertain construction defects once the new home construction is complete. La. R.S. 9:3141 et seq. These protections can prove crucial to a homeowner’s ability to remedy defects that appear in their home, but the statutes providing these remedies establish strict guidelines that must be followed for the protections to apply. This generally post sets forth some of the key protections and obstacles/defenses that often arise. However, each specific claim should be considered under its own facts.

PROTECTIONS

The NHWA provides specific protections to homeowners. Each protection expires if not advanced within a set time-period.

Noncompliance/Defects- The NHWA protects against “any defect due to noncompliance with the building standards or other defects in materials or workmanship not regulated by building standards.” La. R.S. 9:3144(A)(1). This category includes defective construction or materials used in the construction. Even seemingly minor issues such as cracked plaster, yellowing paint, and “rubbing off” of new paint can give rise to a valid claim for recovery under this portion of the NHWA. See Bynog v. MRL, LLC, 05-122 (La. App. 3 Cir. 6/1/05), 903 So.2d 1197. Deviations from the “plans and specifications” for a home may also be recoverable. See Thorn v. Caskey, 32-310 (La. App. 2 Cir. 9/22/99), 745 So.2d 653.

Because this first protection is so broad, it also provides the shortest time-period to assert a claim: one year from the “warranty commencement date,” which is either the date legal title to the home is conveyed to its initial purchaser or the date the home is first occupied, whichever occurs first. La. R.S. 9:3142(7).

Plumbing/Electrical/HVAC- The NHWA also protects the homeowner from defects in the plumbing, electrical, heating, cooling, and ventilating systems. These protections exclude equipment or appliances. A homeowner must bring a claim under this second category within two years of the warranty commencement date. La. R.S. 9:3144(A)(2).

Major Structural Problems- the NHWA allows recovery for major structural defects up to five years following the warranty commencement date. La. R.S. 9:3144(A)(3). For instance, recovery was allowed for a failing foundation under this provision in Campo v. Sternberger, 15-53 (La. App. 5 Cir. 11/19/15),179 So.3d 908.

PITFALLS

The most obvious – and probably most prevalent – pitfall is the timeliness of the claim. Courts do not hesitate to dismiss a claim if it is not timely filed.

The NHWA also requires that the homeowner give the builder written notice (via certified mail) of the defect before the homeowner attempts a repair, or before filing suit under the NHWA. La. R.S. 9:3145(A). This notice must be sent to the builder within one year after the homeowner has knowledge of the defect. Therefore, the one-year “clock” may begin to run when the homeowner gains knowledge of the problem even if the NHWA provides a longer time-period to advance the claim.

A failure by the homeowner to give timely notice can also diminish the claim even if it is brought within the deadlines. Under La. R.S. 9:3144(B)(4)(c), any damages caused by the homeowner’s failure to give the builder notice of the defect are not recoverable. In that circumstance, builders often contend that the severity of the problem could have been lessened had they been made aware.

RECOVERABLE DAMAGES

With some exceptions, damages under the NHWA are limited to the actual damages incurred by the homeowner, including attorney fees and court costs arising out of the builder’s violation. La. R.S. 9:3149. The actual damages cannot exceed the reasonable cost of repair or replacement necessary to cure the defect. If there are multiple defects across the home, damages are limited to the original purchase price of the home.

Consequential damages such as pain and suffering, mental anguish, or loss of use are generally not recoverable. See La. R.S. 9:3144(B); Iteld v. Four Corners Const., L.P., 12-1504 (La. App. 4 Cir. 6/5/13), 157 So.3d 702. However, there may be exceptions to this general rule under certain factual circumstances beyond the scope of this post.

CONCLUSION

The NHWA provides important remedies to homeowners. But, the New Home Warranty Act is complex and balances the competing interests of the homeowners and the builders. For this reason, a failure to follow the notice and timeliness requirements will often defeat the claim.

John Grinton, is a partner at Keogh Cox whose practice areas include commercial and construction litigation. When he is not practicing law, John spends most of his time with his wife and son, and their two dogs.
Insight

Third-Party Criminal activity: Is Summary Judgment Available in a Premises Liability case?

The liability of a premises owner for third-party criminal acts has been the subject of many decisions issued by the Louisiana Supreme Court. But recently, the Court clarified how to analyze this issue in the context of summary judgment. In Campbell v. Orient-Express Hotels Louisiana, Inc. (Windsor Court), the Supreme Court reversed the court of appeal and held that Windsor Court was not liable for a robbery that occurred in its courtyard.

The factual background is simple: Campbell was a frequent guest at the Windsor Court. He decided to approach a vehicle near the entrance to the courtyard when he pulled a “substantial amount of cash” to show the female occupants in the vehicle. He placed the money back in his pocket and talked with them for one minute and forty-six seconds. When he pulled the cash from his pocket a second time, one of the occupants grabbed the cash and the vehicle sped away dragging him with it. Campbell then sued the Windsor Court alleging negligence, strict liability, failure to warn, failure to ensure the safety of its guests, etc.

The importance of this decision is found in how the Court analyzed the case to reach its conclusion that summary judgment was proper: The Court noted that it was not modifying prior duty/risk analysis but was clarifying how the analysis is to be conducted—The issues of “duty” and “scope of duty” are separate inquiries that require separate analysis.

In Campbell, the Court acknowledged that “duty” is a question of law for the court. It then concluded that “(w)hether a particular risk falls within the scope of that duty, by contrast, ‘is fact sensitive and ultimately turns on a question of policy as to whether the particular risk falls within the scope of that duty.’” However, the court continued, “‘(t)he determination of legal cause/scope of the duty involves a purely legal question.’” The Court conducted an historical analysis noting that prior decisions had “merged the concept of duty and scope of duty into a single consideration.”

On the threshold question of duty, the Court acknowledged that in the context of third-party criminal activity, Windsor Court, as an innkeeper, owed a duty to take reasonable precautions to protect its patrons from criminal acts of third parties. Having found this duty, the Court then concluded that “Campbell cannot meet the ‘scope of the duty’ element of his claim.” In other words, “the scope of the duty owed by the Windsor Court did not encompass the risk of the particular harm and Injury Mr. Campbell suffered.”

Here the court asked whether this particular risk and injury were “foreseeable.” The Court examined multiple factors to find that the robbery was not foreseeable, but the Court further noted “perhaps even more important to our decision is the manner in which the robbery occurred.” Campbell was not unexpectedly accosted, but his own actions placed him in peril. As such, the Court found no “ease of association” between Windsor Court’s duty to take reasonable precautions to protect its guests and the risk that the guest would voluntarily approach an unknown vehicle and flash a sizable pile of cash.

Justice Crain concurred in the opinion and noted that “scope of duty can be resolved on summary judgment if reasonable persons could not disagree that the manner of the injury is either within or beyond the scope of the duty.” Justice Crain also noted that the manner of injury must be analyzed in the context of “foreseeability” from the perspective of the premises owner and have an “ease of association” between the duty and the manner of injury—this analysis is necessary to “avoid making a defendant the insurer of all persons against all harms.” Thus, he agreed with the majority that Campbell was unable to establish the scope of duty element.

Reference:

Campbell v. Orient-Express Hotels Louisiana, Inc., 2024-00840 (La. 3/21/25), 403 So. 3d 573.

Insight

Louisiana First Circuit Finds for State Trooper in Fatal Shooting

On July 27, 2023, the Louisiana First Circuit entered judgment in favor of Louisiana State Trooper Andre Bezou in the shooting death of Coltin LeBlanc. The case was defended by Keogh Cox attorneys Drew Blanchfield, Brian Butler, and Collin LeBlanc. In support of its ruling, the First Circuit cited La. R.S. 9:2798.1 which provides qualified immunity for an officer’s actions, unless their action constituted “criminal, fraudulent, malicious, intentional, willful, outrageous, reckless, or flagrant misconduct.” The court found Trooper Bezou was entitled to qualified immunity under the facts of this case.

After midnight in an area of Hammond, La. dotted with bars and restaurants, Trooper Bezou spotted LeBlanc driving a large Ford truck. Trooper Bezou testified that he witnessed two traffic violations and initiated a stop. “Bodycam” footage captured the interaction. LeBlanc exited the vehicle, and when the trooper asked for identification, LeBlanc indicated it was in his truck. LeBlanc moved to the cab of the truck, and Trooper Bezou followed, stopping within the open driver’s side door. Based upon his observations during this interaction, Trooper Bezou suspected LeBlanc was intoxicated. Later testing confirmed that LeBlanc had a blood alcohol level more than two times the legal limit.

But LeBlanc was not attempting to retrieve his license. Instead, he revved the engine and attempted to flee with Trooper Bezou immediately next to the vehicle. Trooper Bezou later testified he feared that LeBlanc would steer the vehicle to run him over with the back left wheel. In reaction, Trooper Bezou latched onto the truck and LeBlanc sped around a corner and down the roadway. Trooper Bezou was able to draw his weapon and gave multiple orders to stop. Trooper Bezou testified that he feared he would be thrown from the vehicle or scraped against parked cars in the area. When the trooper received no indication LeBlanc would relent, he opened fire. Thereafter, the truck came to a rest.

In the subsequent litigation, plaintiffs argued that Trooper Bezou used “excessive force” and should have attempted to move away and allow LeBlanc to flee the scene. In response, Keogh Cox cited Harmon v. City of Arlington, 16 F.4th 1159 (5th Cir. 2021), where the federal Fifth Circuit held that no “clearly established precedent” would prohibit an officer from firing while perched on the running board of a fleeing vehicle. Finding no excessive force under the facts of the case, Harmon acknowledged the simple truth that “there is an obvious threat of harm to an officer” who is “on the side of a fleeing vehicle.” The facts presented to the First Circuit showed that Trooper Bezou gave more warning to relent than was given in Harmon.

The New York Times covered this incident in an article titled, “Before the Final Frame: When Police Missteps Create Danger.” 11/17/21. In its coverage, the New York Times reported that Trooper Bezou “appeared to be in grave danger.” It then suggested that the trooper could have just backed away. However, courts are instructed not a gauge questions of immunity from an out-of-context application of “20/20 hindsight.” Because the facts in this case showed Trooper Bezou was in grave danger “at the moment” force was used and was faced with a split-second decision, he was protected from liability.

No items found.
Property
Real Estate
Summary Judgment